
Recap | Week Ahead | AI Evolving
“It’s not whether you get knocked down, it’s whether you get up.” – Vince Lombardi
Last week's market recap:
- The S&P 500 closed the week down -2.67%. Year-to-date the index is up 8.78%
- NASDAQ closed the week down -3.37%. YTD the index is up 6.25%
- U.S. Aggregate Bond index closed the week up .40%. YTD the index is down -.15%
- 10-Year Treasury Rate decreased, ending the week at 4.86% down from 4.94% the prior week
- Fed Funds Target rate remains at 3.75-4.00%
- The 1-Year Treasury is yielding 4.36%
- A 6-Month Treasury is yielding 4.29%
The week ahead:
- CPI and PPI (Inflation data)
- U.S. / Iran Conflict
- Corporate Earnings: Occidental Petroleum, Applied Materials, Cisco, KKR, and many more.
AI Is Evolving, Not Ending
Is this the pause that refreshes?
Markets took investors on a wild ride last week following the midterm elections. Stocks initially rallied as the election results reduced some political uncertainty, but that optimism quickly faded as investors turned their attention back to the biggest question facing markets: How much longer can the AI investment cycle continue at its current pace?
The result was a sharp selloff in tech and AI-related stocks, with the Nasdaq entering correction territory and volatility jumping significantly.
But this looks more as a reset than a retreat.
The AI story is undergoing a shift. For the past several years, investors rewarded companies that supplied the “picks and shovels” of the AI buildout—semiconductors, data centers, cooling systems, power infrastructure and electrical equipment. Now, the focus is increasingly moving from AI investment to AI economics: How much will companies spend, how quickly will those investments generate returns, and which businesses will ultimately capture the productivity gains?
That shift could create a different group of winners.
Companies with strong balance sheets, healthy cash flow, and the ability to fund massive investments internally may have an advantage. The mega-cap technology companies are particularly well positioned because they can continue investing through a period when smaller or more highly leveraged companies may struggle with higher financing costs.
At the same time, the next wave of AI beneficiaries may come from outside technology. Healthcare, financials, industrials and other businesses that successfully use AI to lower costs and improve productivity could become increasingly important to market leadership.
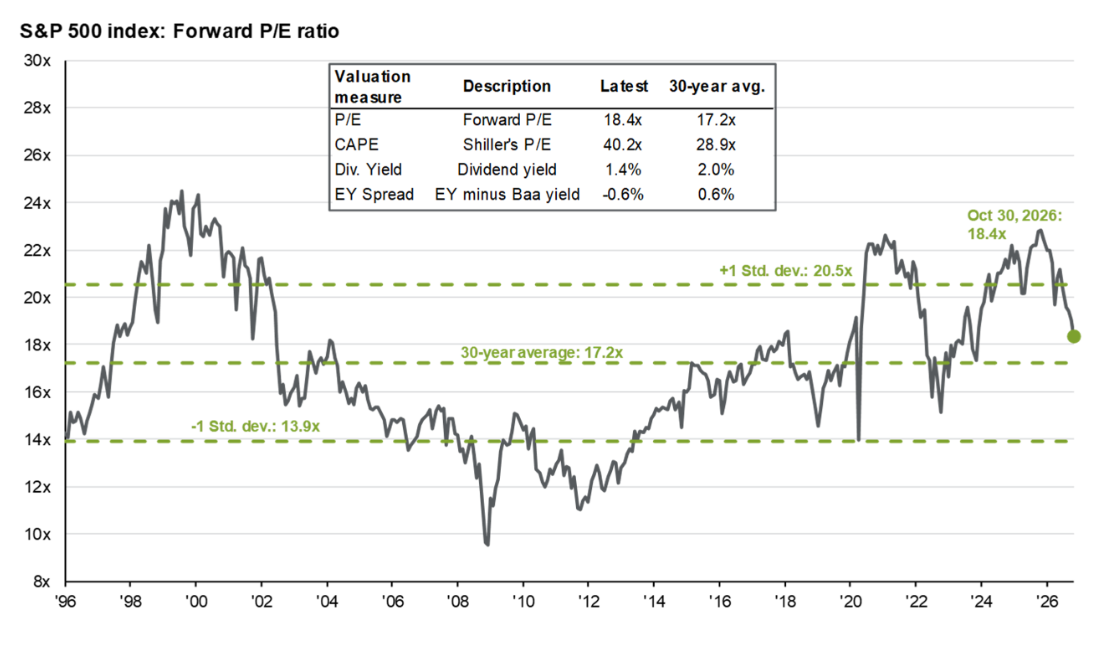
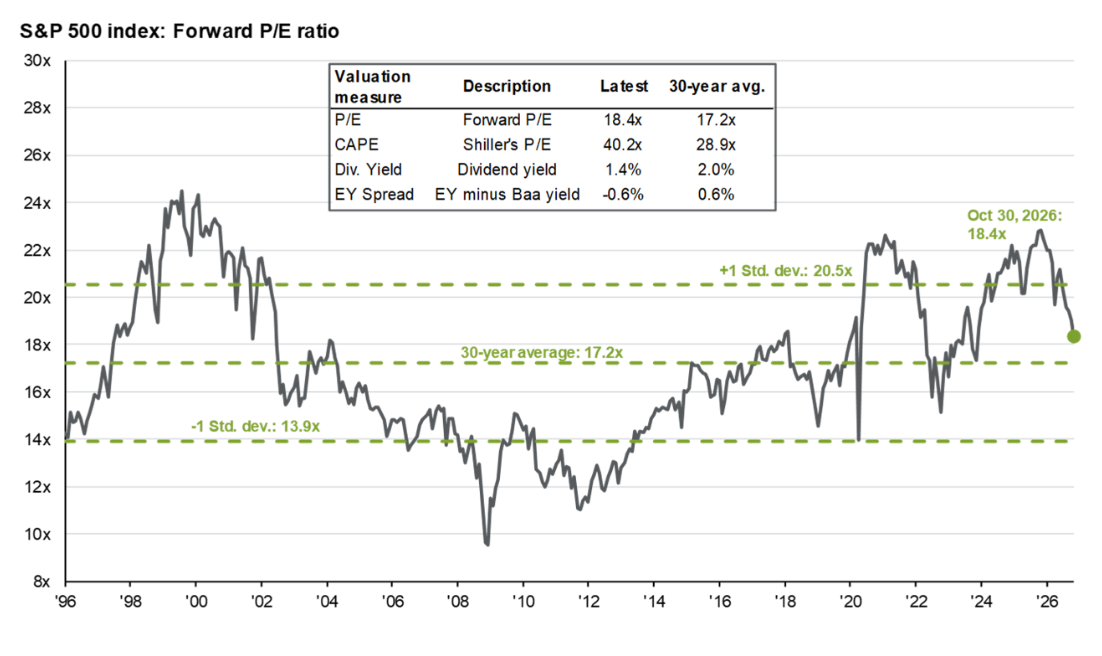
The encouraging part is that the underlying economy remains relatively healthy. Consumers are holding up, retail activity remains solid and fundamental earnings growth has not disappeared. Meanwhile, valuations have come down meaningfully, making some high-quality companies more attractive than they were several months ago.
That doesn’t mean investors should rush to buy everything that has fallen. Selectivity matters. But after several months of valuation compression, price action is beginning to entice investors back into areas of the market that were previously priced for perfection.
The bottom line: This looks more like a pause that refreshes than the end of the AI bull market. The next phase may simply be more selective, with balance sheets, cash flow, valuation and actual productivity gains driving returns rather than simply exposure to the AI theme.
For long-term investors, volatility can be uncomfortable—but history has repeatedly shown that some of the best opportunities emerge when sentiment changes faster than the underlying fundamentals.
As always, let us know if you have any questions.
Best,
CRA Investment Committee
Matt Reynolds CPA, CFP®
Tom Reynolds, CPA
Robert T. Martin, CFA, CFP®
Joe McCaffrey, CFP®
Gordon Shearer Jr., CFP®
Jeff Hilliard, CFP®, CRPC®
Phillip Tompkins, CFP®
Important Disclosure Information
Please remember that past performance may not be indicative of future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product (including the investments and/or investment strategies recommended or undertaken by CRA Financial, LLC [“CRA]), or any non-investment related content, made reference to directly or indirectly in this commentary will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions. Moreover, you should not assume that any discussion or information contained in this commentary serves as the receipt of, or as a substitute for, personalized investment advice from CRA. Please remember to contact CRA, in writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you would like to impose, add, or to modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. CRA is neither a law firm, nor a certified public accounting firm, and no portion of the commentary content should be construed as legal or accounting advice. A copy of CRA’s current written Disclosure Brochure discussing our advisory services and fees continues to remain available upon request or at www.crafinancial.com. Please Note: If you are a CRA client, please advise us if you have not been receiving account statements (at least quarterly) from the account custodian.
Historical performance results for investment indices, benchmarks, and/or categories have been provided for general informational/comparison purposes only, and generally do not reflect the deduction of transaction and/or custodial charges, the deduction of an investment management fee, nor the impact of taxes, the incurrence of which would have the effect of decreasing historical performance results. It should not be assumed that your CRA account holdings correspond directly to any comparative indices or categories. Please Also Note: (1) performance results do not reflect the impact of taxes; (2) comparative benchmarks/indices may be more or less volatile than your CRA accounts; and, (3) a description of each comparative benchmark/index is available upon request.
Please Note: Limitations: Neither rankings and/or recognitions by unaffiliated rating services, publications, media, or other organizations, nor the achievement of any professional designation, certification, degree, or license, or any amount of prior experience or success, should be construed by a client or prospective client as a guarantee that he/she will experience a certain level of results if CRA is engaged, or continues to be engaged, to provide investment advisory services. Rankings published by magazines, and others, generally base their selections exclusively on information prepared and/or submitted by the recognized adviser. Rankings are generally limited to participating advisers (to the extent applicable). Unless expressly indicated to the contrary, CRA did not pay a fee to be included on any such ranking. No ranking or recognition should be construed as a current or past endorsement of CRA by any of its clients. ANY QUESTIONS: CRA’s Chief Compliance Officer remains available to address any questions regarding rankings and/or recognitions, including the criteria used for any reflected ranking.